Category: Economy

  • DMO Scales Back August Bond Issuance to N1.1 Trillion Despite High Demand

    DMO Scales Back August Bond Issuance to N1.1 Trillion Despite High Demand

    Nigeria’s Debt Management Office (DMO) cut its Federal Government bond offer to N1.1 trillion for its August 2026 primary market auction, stepping back offering volumes despite absorbing heavy investor demand during the previous month’s sale.

    The debt office re-opened three benchmark maturities on Monday, August 17: a 10-year paper maturing in January 2035 offered at N250 billion with a 22.60% coupon, a 20-year paper maturing in April 2037 pegged at N100 billion with a 16.25% coupon, and a 15-year paper maturing in June 2038 accounting for the lion’s share at N750 billion with a 15.45% coupon.

    The decision to scale back auction size comes on the heels of the DMO pulling in over N1.74 trillion in total investor bids during July’s issuance. Local institutional fund managers, pension fund administrators, and commercial treasury desks flooded the prior auction seeking high sovereign yields, allowing government debt managers to easily meet target capital allotments.

    Financial analysts noted that reducing the August issuance target allows debt managers to prevent over-supplying the fixed-income market while keeping borrowing costs from escalating further. With high inflation pushing market yields upward, maintaining tighter supply helps sovereign issuers manage long-term debt servicing burdens on federal revenues.

    Primary market subscriptions remained structured for high-net-worth investors and institutional managers, requiring a minimum entry bid of N50 million with increments of N1,000 thereafter. Successful bidders pay a clearing price corresponding to the yield-to-maturity bid that clears the auctioned volume, alongside accrued interest on re-opened issues.

    The government securities retain full backing by the federal government and qualify as liquid assets for bank liquidity ratio calculations, as well as tax-exempt assets for pension funds under current revenue laws. Official auction results and settlement data are distributed through the Debt Management Office Portal. Investors tracking secondary market trading volumes can check updates on the FMDQ Exchange.

  • Nigeria’s Textile Mills Leave 47% Capacity Idle as Import Ban Debated

    Nigeria’s Textile Mills Leave 47% Capacity Idle as Import Ban Debated

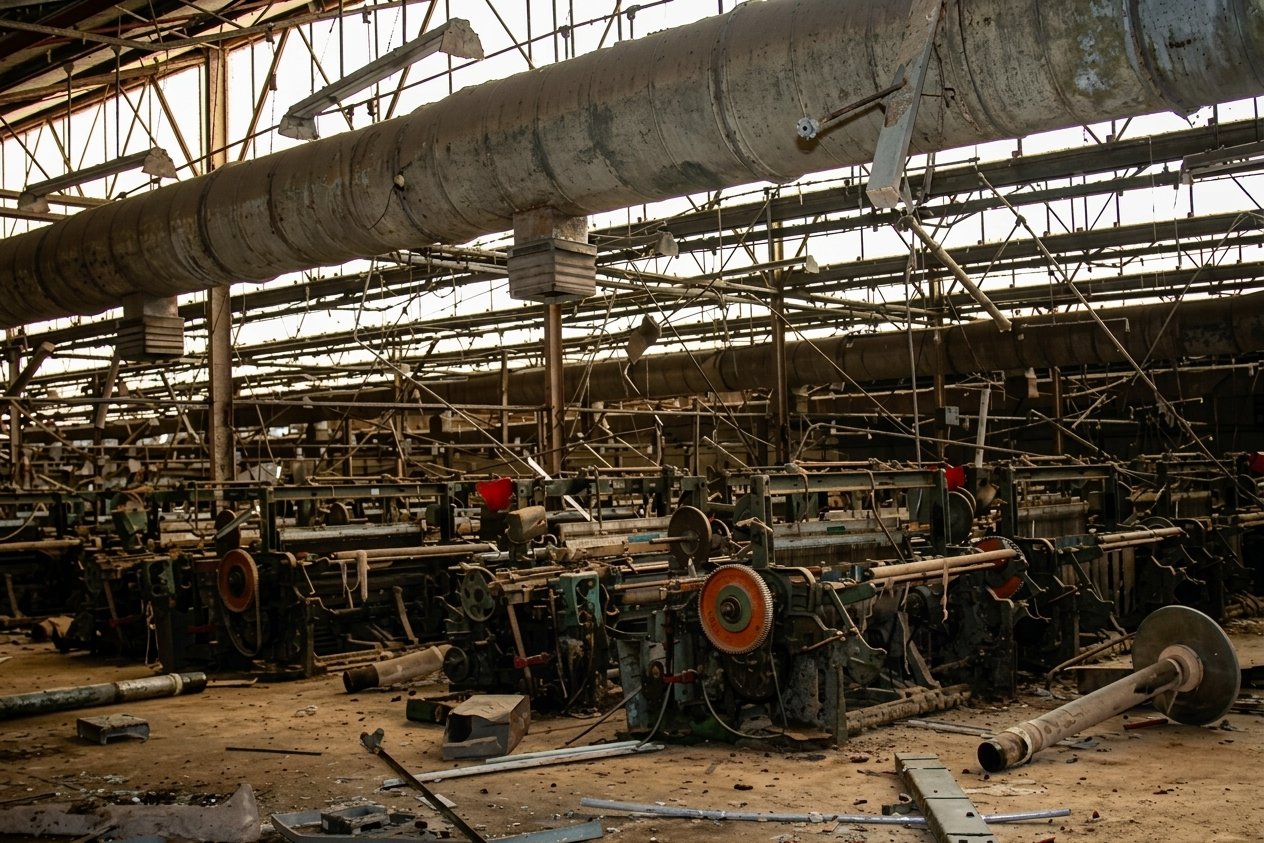
    Nigeria’s textile, apparel, and footwear manufacturers operated at just 53.05% of their installed capacity over the past year, leaving nearly half of the country’s domestic production potential entirely idle.

    Data analyzed from the Central Bank of Nigeria and National Bureau of Statistics bulletins reveals a minor uptick from 50.72% capacity utilization in 2024. But the sector remained pinned below 55% across all four quarters, underscoring the deep-seated structural bottlenecks choking off local factory floors.

    The figures arrive at a tense moment for the nation’s industrial policy. The Nigerian Senate is pressing for a total ban on textile imports to plug a $6 billion annual drain in foreign exchange and protect domestic mills. Yet trade experts warn that forcing an import ban when fewer than 20 operational textile mills remain standing risks creating massive market shortages.

    “The Senate is right that our textile industry must be revived,” said Prof. Adesoji Adesugba, an industrial strategist and former investment promotion chief. “But an immediate import ban would hand the market to smugglers and repeat 30 years of costly failure.”

    The collapse of local cotton farming has compounded the crisis. National cotton production plummeted from 2.5 million metric tonnes in 2001 to 10,000 metric tonnes in 2025.

    Compounding the raw material shortage are crippling power bills and high borrowing costs. Textile manufacturing relies heavily on continuous power for spinning, weaving, and wet processing, leaving producers exposed to expensive diesel generation and rising grid tariffs.

    Producers also face prohibitive interest rates that make modernizing obsolete equipment nearly impossible. Manufacturers Association of Nigeria Director-General Segun Ajayi-Kadir has repeatedly cited expensive capital and foreign exchange scarcity as major drags on output across the broader industrial sector.

    Decades of government intervention—including the 100 billion naira Cotton, Textile and Garment Fund and 2019 central bank forex restrictions—have struggled to reverse the decline. Analysts contend that until energy tariffs stabilize, rural security improves for cotton farmers, and long-term single-digit financing becomes available, Nigerian textile mills will continue operating at half capacity.

  • Nigeria Banking Liquidity Drops 30%: Impact on Loans and Interest Rates

    Nigeria Banking Liquidity Drops 30%: Impact on Loans and Interest Rates

    Nigeria’s banking sector has entered a new phase of monetary tightening. While balance sheets show high overall capital reserves, the cash flowing freely between commercial lenders is shrinking fast.

    Data from the Central Bank of Nigeria (CBN) shows average net liquidity in the financial system fell 30.07 percent to N4.72 trillion in April 2026, down from N6.75 trillion in March. The drop reflects deliberate policy interventions designed to absorb free cash and re-anchor price stability.

    Here is a breakdown of what the liquidity figures mean, why cash is leaving the system, and how the shift affects banks, businesses, and everyday borrowers.

    What Is System Liquidity and Why Is It Falling?

    System liquidity refers to the uncommitted cash commercial banks hold to process daily transactions, back client withdrawals, and issue loans.

    The drop in excess cash stems from three distinct operations by the central bank:

    • Open Market Operations (OMO): The CBN issued high-yield debt to suck cash out of circulation. Investors submitted N10.60 trillion in subscriptions for N3 trillion worth of OMO bills offered in April, with N9.51 trillion eventually allotted at an average stop rate of 20.88 percent.
    • Cash Reserve Requirement (CRR): Tight enforcement of cash reserve ratios forced banks to keep a larger share of deposits directly with the regulator.
    • Foreign Exchange Outflows: Sales and transactions in the official foreign exchange market drew additional local currency out of commercial bank balances.

    The liquidity drain showed up directly in bank usage of central bank facilities. Commercial deposits at the Standing Deposit Facility (SDF) fell from N130.69 trillion in March to N91.55 trillion in April. That sharp drop indicates lenders had less cash to leave parked overnight at the central bank.

    How Can Liquidity Fall While Banks Stay Solvent?

    A falling cash supply does not mean banks are in financial trouble. The industry’s overall liquidity ratio actually rose to 74.16 percent in April from 67.32 percent in March—more than double the regulator’s 30 percent minimum requirement. Capital adequacy stood at 13.07 percent against a 10 percent threshold.

    The distinction lies between overall solvency and circulating excess cash. Lenders hold more than enough assets to cover long-term liabilities, but the central bank has reduced the volume of cheap, unallocated cash floating through the interbank market.

    What Does This Shift Mean for Commercial Banks?

    For years, Nigerian lenders generated solid returns by placing surplus cash into safe government securities or funding tier-one corporate clients. That model is facing pressure.

    Yields on government paper are edging lower, and top-tier corporations are pushing for single-digit interest rates. At the same time, the cost of funds remains high. The weighted average deposit rate rose to 8.74 percent in April from 8.36 percent in March, narrowing the spread between deposit costs and maximum lending rates to 26.44 percentage points.

    Speaking ahead of the Chartered Institute of Bankers of Nigeria (CIBN) Annual Conference in Lagos, CIBN President Dele Alabi said banks can no longer rely on easy returns from risk-free assets.

    “Capitalisation provides a buffer for shocks,” Alabi told reporters. “Yields are coming down on government securities, and for top-tier players, margins are thin. Smart bank CEOs have to think of more ingenious ways of utilizing this capital.”

    Alabi pointed to micro, small, and medium-sized enterprises (MSMEs) as the primary area where banks must redeploy capital to generate long-term value.

    What Happens to Borrowers and Business Loans?

    Tighter cash conditions often signal rising interest rates, but April data showed a mixed picture. Average prime lending rates for top-tier corporate borrowers dropped slightly by 0.42 percentage point to 18.87 percent.

    The challenge sits with smaller, informal businesses. With less uncommitted cash in the market, lenders are growing selective. Large conglomerates with strong balance sheets can secure credit at competitive rates, while MSMEs face stringent collateral demands and higher risk premiums.

    If banks heed regulatory nudges to move down the value chain, smaller businesses could gain broader credit access over time. But lenders remain cautious due to asset quality concerns.

    The banking sector’s non-performing loan (NPL) ratio stood at 10.22 percent in April, well above the 5 percent regulatory limit. The CBN attributed the elevated figure to the expiration of regulatory forbearance granted during the COVID-19 pandemic.

    What Does This Mean for the Broader Economy?

    The central bank’s liquidity siphon is designed to curb inflation and keep money market rates aligned with monetary targets. Money market rates stayed within policy bands in April, with the open repurchase rate rising slightly to 22.06 percent from 21.95 percent.

    Demand for government debt remains strong. Treasury bill issuances worth N1.45 trillion attracted N5.32 trillion in total subscriptions in April, while reopening tenders for long-term federal bonds drew N0.95 trillion against N0.70 trillion offered.

    The central economic question is whether commercial banks will continue funneling excess capital into government debt sales or redirect funds toward productive private-sector investments. If capital stays tied up in debt instruments, economic growth could slow. If banks successfully manage risk and expand credit to MSMEs, tighter liquidity could lead to more efficient, productive investment across the country.
  • Court Orders 71 Lenders to Freeze Accounts Over ₦1.3B Access Bank Fraud

    Court Orders 71 Lenders to Freeze Accounts Over ₦1.3B Access Bank Fraud

    LAGOS — A High Court has ordered 71 commercial banks, microfinance institutions and financial technology firms to immediately freeze accounts connected to an alleged ₦1.3 billion fraud at Access Bank Plc.

    The court issued the order following an ex-parte application filed by the bank after internal systems flagged unauthorized electronic transfers siphoned into dozens of third-party accounts across Nigeria’s financial network.

    Judicial documents show the perpetrators routed the stolen funds through a complex web of microfinance banks, digital payment platforms and tier-one commercial lenders in an effort to obscure the transaction trail and move the money out of reach.

    Under the terms of the court order, all 71 affected institutions must place an immediate Post-No-Debit restriction on the target accounts, blocking all withdrawals, transfers and debit transactions until law enforcement agencies complete their investigation.

    Central Bank of Nigeria directives require financial institutions to enforce judicial freeze orders immediately upon receipt to prevent the further dissipation of stolen assets.

    Security agencies and cyber-crime investigators have launched a joint operation to trace the final destination of the funds and identify the syndicates involved in breaching the bank’s security architecture.

    Access Bank officials confirmed that forensic audits are underway to determine whether the security breach originated through external network exploitation, sophisticated phishing operations or insider collusion.

    Financial sector experts noted that the involvement of 71 separate institutions highlights the increasing velocity and fragmentation of cyber-enabled bank fraud in West Africa’s largest economy.

    Nigerian commercial lenders lost tens of billions of naira to electronic fraud schemes in recent years, prompting calls from regulators and security agencies for tighter inter-bank communication protocols and faster asset-recovery mechanisms.

    Court proceedings are expected to resume next month as legal representatives for the affected institutions file compliance reports detailing the total balance of funds successfully trapped.