Accessing formal credit in Nigeria has long required a smartphone, internet connection, and established bank footprint. Those digital prerequisites left millions of small-scale traders and informal workers locked out of the financial system.
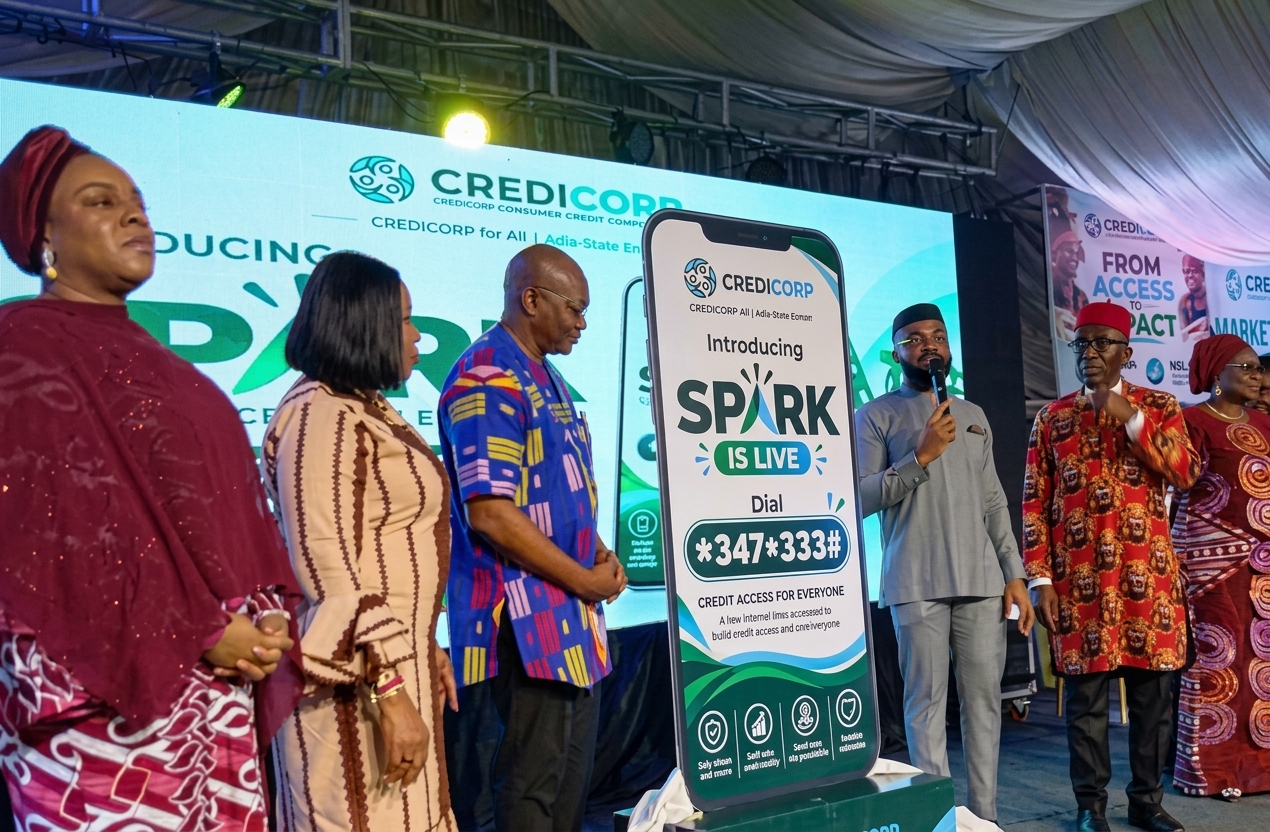
The Federal Government move to bypass those barriers came through the Nigerian Consumer Credit Corporation. Operating under the brand SPARK, the newly introduced USSD credit facilitation service allows citizens to apply for financial products directly from basic feature phones without requiring data or internet access.
Unveiled by CREDICORP during the “CREDICORP for All” showcase event in Aba, Abia State, the platform represents a major structural shift in how consumer credit is deployed across the country.
Why Did the Federal Government Choose the USSD Route?
The decision to deploy consumer credit through Unstructured Supplementary Service Data stems from telecom infrastructure realities.
While smartphone adoption across urban centers continues to grow, feature phones remain the dominant communication tool for millions of rural workers, informal traders, and low-income households. Mobile app-based lending platforms default to internet connectivity, which automatically excludes a massive percentage of the population from accessing formal credit windows.
USSD technology operates over basic GSM networks. By building SPARK on a text-based protocol, the government eliminates hardware inequality, allowing anyone with a working phone line to submit loan applications.
What Is the Official USSD Code for SPARK?
The official USSD code for accessing the SPARK platform is *347*333#.
Applicants can dial the number on any mobile device across participating domestic telecommunications networks. The code launches an interactive text menu that guides users through account registration, credit assessment steps, and partner financial institution options.
CREDICORP advised citizens that while the code was formally introduced during the pilot launch in Abia State, full commercial functionality is rolling out in structured operational phases.
Understanding What SPARK Is and What It Is Not
A critical operational boundary defines the SPARK initiative: it is a structured commercial loan facility, not a government grant or welfare handout.
The scheme does not distribute free funds. Beneficiaries are legally and financially obligated to repay disbursed funds along with interest according to agreed schedule terms.
SPARK operates as a credit facilitation bridge rather than a direct lender. CREDICORP acts as a government development finance institution that provides wholesale funding, risk-sharing guarantees, and technical integration to participating private financial institutions.
Those partner banks and microfinance institutions underwrite the risk, disburse the actual funds, and collect repayments.
How SPARK Helps Low-Income Earners Build Credit Histories
In traditional banking, lack of a formal credit score presents a catch-22: banks refuse to lend without a track record, but individuals cannot establish a track record without initial access to credit.
SPARK breaks this cycle by integrating alternative data points to assess initial creditworthiness for first-time borrowers. The platform evaluates basic identity verification alongside phone usage patterns and transaction footprints to issue small initial credit allocations.
As beneficiaries take small loans and repay them on schedule, their performance data feeds directly into national credit bureaus. This process builds a verifiable, formal credit history for individuals who previously had no recorded financial identity, opening doors to larger commercial loans over time.
What Role Does CREDICORP Play in Financial Inclusion?
The Nigerian Consumer Credit Corporation serves as the central institutional catalyst for expanding consumer credit nationwide.
Rather than competing with private commercial banks, CREDICORP supports the financial ecosystem through three primary operational pillars:
- Capital Provision: Supplying wholesale liquidity and credit guarantees to partner financial institutions so they can lower interest rates and extend consumer loans.
- Infrastructure Building: Partnering with credit reporting agencies and financial technology firms to ensure every working citizen can obtain a functional credit score.
- Cultural Shift: Conducting public education to shift social perceptions toward viewing credit as an economic growth tool rather than a debt trap.
Through these mechanisms, CREDICORP provides financial backing so institutional lenders can expand credit into previously underserved demographics.
Economic Impact: Weighing the Positives and Negatives
The rollout of USSD-based consumer credit brings distinct macroeconomic benefits alongside clear operational risks.
The Positives
Democratizing credit access stimulates immediate consumer demand. When informal traders gain access to small working capital loans, they can purchase inventory, buy equipment like solar power installations, or upgrade personal technology items.
This direct purchasing power channels liquidity back into local producers and domestic manufacturers, aligning with initiatives like the Securing Consumer Access for Local Enterprises program.
Furthermore, shifting informal transactions into formal digital loan pipelines increases overall financial inclusion, expanding the nation’s measurable tax base.
The Negatives
Unlocking consumer credit across populations unfamiliar with structured debt carries default risks. If borrowers view government-backed loans as non-repayable interventions, non-performing loan ratios among partner financial institutions could spike.
High interest rates driven by broader inflation also present a challenge. If macroeconomic conditions remain tight, micro-borrowers may struggle with interest payments, leading to over-indebtedness.
Network uptime risks on USSD channels and potential security threats from fraudulent third-party agents also pose operational hurdles during widespread implementation.